PayID is an Australian payment system that lets a person identify a payment destination with a unique detail, such as a mobile number or email address, rather than relying only on conventional account information. It operates over the New Payments Platform (NPP), the infrastructure that supports rapid transfers between participating banks. For a payment, the identifier serves as the key that connects the transaction to its intended destination within that system.
That description separates two things that are easy to confuse: PayID is the payment method, while the account or service receiving money is a separate matter. Using an identifier does not mean that PayID itself provides gambling games, checks a gambling operator, or decides whether an operator may serve people in Australia. The payment rail carries a transfer; it does not determine what the recipient offers or whether that activity is lawful.
When a payment service presents PayID as a deposit route, the basic idea is that you use the relevant identifier to direct money through your bank’s payment process. The transfer then travels through the NPP between banks. Because the platform is built for quick interbank movement, a PayID deposit at an online casino is typically credited within seconds. That is a description of the payment leg, not a promise about every screen, account or service connected to it.
Список казино
If you’re looking for new PayID pokies in Australia for 2026, use this list as a starting point for checking the details that matter to you. The notes below stick to the information available for each operator.
1
JeetCity Casino
License
Curacao eGaming (Dama N.V.)
JeetCity Casino is listed with a Curacao eGaming licence held by Dama N.V. Check the operator’s terms to see whether its offering suits you.
2
LuckyVibe
License
Curacao Gaming Control Board OGL/2023/176/0095 (Hollycorn N.V.)
LuckyVibe is listed with a Curacao Gaming Control Board OGL/2023/176/0095 licence held by Hollycorn N.V. You can use that licensing detail as a starting point when reviewing the operator.
3
Kingmaker
Payout speed
crypto ~90 minutes, fiat 1-5 days
Min. deposit
A$30
Kingmaker lists a minimum deposit of A$30. Its stated payout times are around 90 minutes for crypto and 1–5 days for fiat.
4
Roby Casino
License
Curacao eGaming (Roby Games Ltd)
Roby Casino is listed with a Curacao eGaming licence held by Roby Games Ltd. You can consider this licensing information when assessing the operator.
5
Playfina Casino
License
Curacao eGaming (Hollycorn N.V., since 2017)
Min. deposit
A$20-30 (depends on the offer)
Playfina Casino is listed with a Curacao eGaming licence held by Hollycorn N.V. since 2017. Its minimum deposit is A$20–30, depending on the offer.
6
Vegaz Casino
License
Curacao OGL/2024/1335/0780
Min. deposit
EUR 20
Vegaz Casino is listed with a Curacao OGL/2024/1335/0780 licence. Its minimum deposit is EUR 20.
7
JustCasino
License
Curacao Gaming Control Board
JustCasino is listed with a Curacao Gaming Control Board licence. You can check the operator’s terms for further details.
8
House of Pokies
License
international iGaming licence – jurisdiction not named in the source
Payout speed
PayID 1-24 hours
Min. deposit
A$30 (PayID from A$10)
House of Pokies has an international iGaming licence, though the source does not name the jurisdiction. PayID payouts are listed at 1–24 hours, with a A$30 minimum deposit or A$10 when depositing via PayID.
9
Ricky Casino
Payout speed
crypto under 1 hour, PayID 1-3 business days
Min. deposit
A$20 (A$30 to qualify for the bonus)
Ricky Casino lists crypto payouts in under 1 hour and PayID payouts in 1–3 business days. The minimum deposit is A$20, rising to A$30 to qualify for the bonus.
10
Lucky Dreams
License
Curacao
Min. deposit
A$20 (POLi)
Lucky Dreams is listed with a Curacao licence and a A$20 minimum deposit when using POLi. You can check its terms for further details.
A delay at another point should not automatically be read as a delay in the NPP itself. A payment page may take time to display an instruction, or a receiving service may need to register the incoming amount before showing it in an account balance. Those are distinct stages from the bank-to-bank transfer. The characteristic speed of PayID concerns the movement of funds through the payment network; it cannot establish how a separate service handles a transaction after it arrives.
This distinction matters when people talk about “new PayID pokies” or a new PayID payment option. “New” may describe a recently opened service, a recently added cashier method, or simply a payment route that is unfamiliar to the user. It does not change how the NPP works. The identifier still directs a transfer through the payment platform, and the underlying speed of the bank transfer is separate from the age or presentation of the service involved.
PayID’s use of a mobile number or email address can make the destination easier to recognise than a string of bank details. The identifier is not itself a separate bank account or a guarantee about the recipient. It is a way of addressing a payment within the system. Treat it as payment information: check what the payment screen is asking you to do and understand that pressing confirm initiates a transfer, rather than merely expressing interest or reserving a transaction.
Payments & Crypto at Australian Casinos
The system is described as supporting fast and secure transactions. That characterises the payment mechanism, not every circumstance around a payment. It does not certify the conduct of a website, the fairness of games, the handling of personal information by another party, or the prospect of receiving money from that party. A familiar payment option may make a transfer easier to initiate, but it is not evidence that the destination is trustworthy or that a gambling service is authorised.
There is also an important Australian legal context. The Interactive Gambling Act 2001 makes it illegal for operators to provide real-money online casino games, including pokies, to people physically located in Australia. PayID’s availability as a general payment system does not alter that rule. A payment technology can be used across many kinds of transactions; its presence on a page does not make the service lawful or endorse it.
For understanding the mechanics, keep the sequence simple: PayID uses a unique identifier to address a payment, the NPP carries the transfer between banks, and a casino deposit made through this route is typically completed within seconds. Each part has a different role. The identifier helps direct the payment, the platform moves it, and the receiving service displays or records it. The seconds figure concerns the deposit transfer and should not be extended into a claim about every step on a website.
If a payment does not appear as quickly as expected, the useful distinction is between the transfer and the recipient’s display of it. PayID is designed for rapid movement between banks, but the payment method alone cannot explain what is happening inside a separate service. Nor does a new label or recently added payment button change the network’s function. The payment mechanism remains the same: an identifier is used to route a bank transfer through Australia’s NPP.
PayID Deposits and Withdrawals: Matching Details, Fees and Reversals
A PayID payment can move money in either direction: from a bank account to a payment recipient, or back to a bank account. For any transaction, the details linked to the payment method matter. A mismatch can create problems before money is sent or when a return payment is requested, so check the account information carefully rather than assuming that a familiar payment option makes the details interchangeable.
There is also an important legal context for Australian readers. Under the Interactive Gambling Act 2001, it is illegal for operators to provide real-money online casino games, including pokies, to people physically located in Australia. The payment process described here does not change that rule or make a service lawful.
Which details need to match
PayID is linked to an identifier registered with a bank, such as a mobile number or email address. The PayID details used for a transaction need to match the PayID registered with that bank. If you enter a different identifier, or use details that are no longer linked to the relevant bank account, the payment may not be handled as you expect.
Safe Online Pokies in Australia: What Safety Means
A secure transaction does not establish an offshore service’s reliability, guarantee withdrawals, or provide meaningful…
Where an account profile is involved, check that the bank account name matches the name on that profile before relying on a payment route. A difference in names can lead to a payment being questioned or a withdrawal failing to reach the intended account. This is separate from checking the PayID identifier itself: the identifier must correspond to the bank’s registration, while the account holder’s name should also be consistent across the relevant records.
Do not assume that a small variation is harmless. A shortened name, an old email address or a mobile number registered to another person may not identify the account you intend to use. If your bank details or PayID have changed, confirm which details are currently registered with the bank before making any payment. If a transaction is declined or cannot be matched, avoid sending another payment until you understand what happened to the first one.
Fees: PayID and other charges
PayID does not impose a transfer fee. Reputable venues also do not add a separate charge simply because a deposit or withdrawal uses PayID. That does not mean every payment arrangement is automatically fee-free: an operator’s own terms may set charges unrelated to PayID, and a bank’s account conditions are separate from the payment system.
Read the stated terms for the particular transaction and distinguish a PayID fee from any other charge. If a fee is described as being for PayID itself, clarify the basis for it before proceeding; the payment method does not charge that fee. Also check the amount that would actually be debited or credited, rather than relying only on a headline claim that a payment is free.
A fee question is different from a matching-details problem. A payment can have the correct PayID details and still be subject to a separate charge under an account or operator policy. Conversely, the absence of a PayID transfer fee does not confirm that the recipient is legitimate, that an account is properly regulated, or that a future payment will be honoured.
Do
Match the PayID identifier with your bank registration
Ensure the bank account name matches your profile
Confirm registered details before making a payment
Don't
Assume small variations in names are harmless
Use an old email or a mobile number registered to another person
Send a second payment if the first is declined or unmatched
Confirmed transfers cannot be reversed
Treat a PayID payment as final once it has been confirmed. PayID transactions are irreversible after confirmation, so you cannot rely on the payment system to cancel or retrieve money simply because you changed your mind or notice an error afterward. This makes checking the recipient and payment details before confirming especially important.
Pause if the recipient information does not match what you expected, if the amount is wrong, or if someone is pressuring you to act before you can verify the details. Do not confirm on the assumption that a mistaken transfer can be undone later. If you have already sent money to an unintended recipient, contact your bank promptly and explain what happened. A bank may be able to advise on the available steps, but that does not make a confirmed transfer reversible or guarantee recovery.
Keep a record of the transaction confirmation and any related correspondence. If a payment is disputed, those records can help you explain which details were entered and when the transfer was confirmed. Avoid sending a second payment to “fix” an unclear first one until you have checked its status with the bank.
The same caution applies to money moving back to a bank account. PayID supports withdrawals as well as deposits, but the receiving details still need to correspond to the account and PayID registered with the bank. Check the account holder’s name and the registered identifier; do not treat the fact that money can move in both directions as a guarantee that a recipient will accept or return it.
Online Pokies in Australia: Bitcoin and Payouts
The guide explains offshore service restrictions, Bitcoin game credits and transactions, and why bonuses and…
These checks are basic safeguards, not an endorsement of any gambling service. PayID availability does not establish that an operator is lawful in Australia, nor does it prove fairness or a willingness to pay. If a payment request involves real-money online pokies for people in Australia, remember that operators are prohibited from providing that service under Australian law.
PayID in Australia: Bank Limits and Transfer Blocks
A PayID transfer can be stopped before it reaches its destination, even when the identifier is correct and the payment details have been entered properly. In Australia, the bank sending the money controls the customer’s daily PayID transfer limit. That limit is a bank-set condition, not a universal PayID allowance, so it can differ between customers and financial institutions. There is no single daily figure that applies to every account.
A specialist gambling-payment review reports that some Australian banks, including Big Four banks, occasionally block PayID transfers to merchants they identify as gambling-related. The report describes a possibility, not a rule that applies to every bank or every payment. A transfer may therefore be declined because of a bank’s acceptable use policy, even if PayID appears as an available payment method at the receiving end.
Your bank controls the sending limit
PayID operates through Australia’s New Payments Platform, but that shared payment infrastructure does not set one daily limit for all customers. The relevant limit is determined by the bank holding your account. If a transfer is larger than the limit applied to your account, your bank may not allow it to proceed. A bank may also apply other conditions to particular payments.
For a declined or delayed transfer, first identify which part of the transaction has stopped. A bank-side limit or restriction is different from a receiving service’s payment processing. If your bank does not authorise the transfer, the receiving service cannot resolve that bank decision by changing its own payment settings. Contact your bank through its usual support channels to ask whether a limit or policy restriction applies. Do not assume that trying the same payment repeatedly will change the result.
The distinction matters because a payment screen may show PayID as an option without confirming that your own bank will approve a transfer to a particular recipient. Availability at one end and authorisation at the other are separate matters. A successful transfer on a previous occasion also does not establish that a later one will be accepted: bank limits and decisions apply to the account and payment being assessed.
A bank block is not a processing delay
If a bank blocks a payment, that is not the same as a receiving service taking time to process it. The bank is deciding whether to send the funds; the recipient’s processing begins only if the transfer is allowed to proceed. Treating both situations as a generic “PayID delay” can make it harder to find out what happened.
Check the payment status shown by your bank and ask the bank whether the transfer was declined, held, or never submitted. If the bank confirms that it sent the payment, any later question belongs with the recipient’s payment support. If it confirms a restriction, the issue is with the bank’s decision rather than the recipient’s processing. Keep the wording of any bank message and the transaction details available when asking for help, but do not share passwords or security codes.
Bitcoin Pokies Australia: Payments, Credits and Protections
The guide explains Bitcoin-funded play, game-credit values, offshore operators, verification checks and what to do…
A block does not by itself show that PayID is unavailable throughout Australia. Nor does an accepted transfer show that the recipient has any particular legal status. PayID is a way to move funds between accounts; it is not an assessment of the recipient or the service receiving the payment.
The Australian legal context
For anyone searching for new PayID pokies in Australia in 2026, payment access should not be confused with whether a real-money online casino service may lawfully be provided to people in the country. Under the Interactive Gambling Act 2001, operators are prohibited from providing online casino-style gambling, including pokies, to customers physically in Australia. The law concerns the provision of the service; a bank’s handling of a payment is a separate question.
That separation is important in both directions. A bank’s refusal to send money does not determine the legal status of an operator, and a transfer that goes through does not establish that the service is lawful, fair, or willing to pay. Bank approval is a payment decision, not an endorsement. Likewise, an option displayed in a cashier does not override Australian law or the policies of the bank sending the funds.
If you encounter a block, do not treat it as a prompt to find another route around the bank’s policy. Ask the bank what restriction applies and follow its instructions. The key practical point is that PayID’s national payment infrastructure does not remove the account-level limits and decisions made by individual banks. A payment can be correctly addressed yet still be stopped before it is sent.
What “New PayID Pokies” Means for Payment Timing
The word “new” does not tell you how a PayID withdrawal will be handled. It may describe a recently introduced service, but it does not establish how quickly a withdrawal request will be reviewed, when funds will leave the casino’s system or how long the receiving bank will take to show the transfer. Those are separate stages, and the casino’s own procedures matter more to the overall wait than the label attached to it.
A PayID withdrawal is not simply the reverse of a rapid deposit. Once a withdrawal is requested, the casino may first review the request internally. Only after it approves the payment does the transfer stage begin. A quick bank transfer cannot remove time spent waiting for that internal decision, so it helps to distinguish “requested,” “pending,” “approved” and “received” rather than treating them as one event.
The casino’s review comes first
Casino-initiated withdrawals may be held in a pending state before the money leaves the casino’s system. Specialist reviews describe pending periods of 24–72 hours in some cases, but this is not a fixed rule for every operator or request. The length of the review can differ, and the time shown in an account may refer only to the casino’s processing rather than to the full interval until funds arrive.
Internal review and identity checks can affect the wait. Specialist reviews report that payout timing depends in part on the casino’s review and the player’s KYC status. If identity verification is incomplete or further checks are required, approval may take longer than the transfer itself. This distinction is useful when interpreting a status: a request that remains pending has not necessarily reached the bank-transfer stage.
Pay by phone casinos in Australia: payment checks
PayID moves money through a bank, while carrier billing charges a mobile account or prepaid…
The status wording can also be easy to misread. “Processing” may mean the casino is still considering the request, while “approved” indicates that its review has been completed and the payment can proceed. The exact labels vary, so rely on the explanation provided in the account rather than assuming that a single status means the money has already been sent. If a displayed estimate applies only after approval, it does not include time spent waiting for that approval.
Approval and transfer are separate clocks
Once a withdrawal is approved, PayID can move the payment quickly between accounts. Specialist reviews describe approved PayID withdrawals as commonly reaching the account within the same day, and report a 12–24-hour transfer window after approval. These are reported timeframes, not promises: the actual arrival time can depend on the operator’s handling and the circumstances of the request.
That timing should not be confused with the full time from submitting a withdrawal to receiving money. A specialist review describes the casino’s pending period as capable of extending the overall process to 2–4 days. The same review material reports that some casino-initiated withdrawals may remain pending for 24–72 hours before funds leave the casino’s system. These figures describe different parts of the process, and neither should be read as a universal schedule.
For instance, a payment could move promptly after approval but still take longer overall because the request spent time under review first. Conversely, a casino may approve a withdrawal without a lengthy pending period, after which the transfer stage is the remaining wait. “PayID is fast” therefore describes the payment rail, not a guaranteed end-to-end withdrawal time.
What “new” can and cannot tell you
A newly introduced PayID option does not, by itself, show whether withdrawals are processed automatically, reviewed manually or held before release. Nor does the word “new” establish that a service has tested its withdrawal procedures over time. The relevant timing details are the stated review process, any pending period, the estimate after approval and the conditions that may delay verification.
If you are assessing a payment timetable, look for wording that separates these stages. An estimate that starts “after approval” excludes the casino’s review. A stated pending period concerns time before funds leave the operator’s system. The bank-transfer estimate concerns the final movement of money. Comparing estimates is meaningful only when they refer to the same starting point.
Australia’s legal setting is also important: the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games, including pokies, to people physically located in Australia. A payment method or a claim about speed does not change that position. Descriptions of withdrawal timing should not be mistaken for evidence that an online casino service is lawful or that a payment will be made.
The practical takeaway is to treat each estimate as conditional and identify which stage it covers. The casino’s review can delay release; the PayID transfer begins only after the payment is approved. The word “new” does not shorten either stage, and a rapid transfer mechanism cannot guarantee a particular date of receipt.
PayID’s Practical Benefits—and What They Don’t Guarantee
PayID has practical features that can make a payment feel straightforward: a deposit may arrive within seconds, the method can be used for payments in both directions, and PayID itself does not add a transfer fee. Those are features of the payment method. They should not be read as evidence that a gambling service is lawful, fair or likely to pay out.
Aristocrat Online Pokies in Australia: What to Know
The search phrase does not establish who made a game or where it is available,…
That distinction matters in Australia. Under the Interactive Gambling Act 2001, providing real-money online casino games, including pokies, to people in Australia is illegal. A payment option does not change that legal position. If a site displays PayID, that only tells you something about the payment route it presents; it does not make the service authorised or establish that it will handle a transaction as promised.
Speed can help with a deposit, not assess the service
PayID deposits at online casinos are typically completed within seconds. Where a payment is accepted and the receiving service credits it promptly, that can reduce the wait between sending money and seeing the deposit reflected in an account. The speed is a useful practical feature, but it describes the transfer—not the quality or status of the service receiving it.
A quick deposit does not show that the site has been independently checked, that its games are fair, or that its terms are clear. Nor does it establish that a later withdrawal will be approved. Payment movement and the decisions made by a casino are separate matters. A payment method can move funds quickly while leaving every question about the operator unanswered.
It is also important not to treat a smooth payment screen as an endorsement. A site may display a familiar payment name and appear professionally presented, but neither appearance nor payment access proves that it is lawful to offer real-money casino games to Australians. The legal restriction applies to the service, not just to the method used to fund it.
Instant Deposits
Payments are typically completed within seconds, reducing the wait to see funds in an account.
Two-Way Movement
PayID supports both deposits and withdrawals, allowing funds to move in either direction.
No Transfer Fees
PayID itself does not charge a fee for transfers, making the method less costly at the transfer level.
Two-way movement is not a payout promise
PayID can support both deposits and withdrawals, with money moving quickly in either direction. That two-way capability is convenient in a narrow sense: the payment method is not limited to sending money into an account. But the existence of a withdrawal route should not be mistaken for a promise that a particular request will be accepted or completed.
A withdrawal involves more than the payment network. The operator may have to review the request and decide whether to release the funds; the transfer method cannot make that decision for it. So the fact that PayID can carry money back does not establish a casino’s willingness to pay winnings, nor does it prove that funds will be available when requested.
Keep the distinction in mind if a site presents PayID as a reason to trust it. A payment feature can describe how a transfer is intended to move, but it cannot establish the operator’s conduct. If a withdrawal is delayed or refused, the existence of a fast payment rail alone does not resolve the underlying dispute.
No PayID transfer fee is not the same as no cost
PayID itself does not charge a transfer fee. Reputable venues also do not add separate charges for PayID deposits or withdrawals. That can make the payment route less costly at the transfer-method level.
However, a statement about PayID fees is not a blanket assurance about every charge associated with an account or transaction. The key point is limited: PayID does not impose its own transfer fee. An operator’s terms and practices are a separate matter, and the presence of PayID does not establish that a service is reputable. Do not infer a broader cost guarantee from the fact that the payment method itself is fee-free.
This is another reason to separate the payment method from the service using it. The transfer can have a clear, simple fee structure while the operator’s own rules remain a different question. A familiar payment option does not verify those rules or make the operator’s claims reliable.
What these benefits cannot tell you
The practical advantages are real but narrow: deposits may be completed within seconds, PayID can carry payments in both directions, and PayID does not charge a transfer fee. None of those points establishes licensing, fairness, transparent game outcomes or a willingness to release funds.
In Australia, this distinction is especially important because real-money online casino services are prohibited when provided to people in the country. PayID access should not be treated as a way around that restriction or as proof that a site is legitimate. A fast transaction is only a fast transaction; it is not a safety check, a regulatory approval or a payout guarantee.
If a payment has already been made, avoid sending further funds simply because a site describes PayID as instant or fee-free. Those features do not settle whether a service is lawful or whether it will honour its own statements. Keep records of what was sent and what the service communicated, and seek appropriate help if you are worried about a payment or gambling-related harm.
What are the typical deposit and withdrawal minimums?
Deposits commonly fall between AU$10 and AU$20, while minimum withdrawals are typically in the AU$20–AU$50 range.
Are there any fees associated with PayID withdrawals?
While PayID has no transfer fee, some operators may charge AU$2–AU$5 for withdrawals or deduct AU$5–AU$10 for amounts below specific internal thresholds.
How long do PayID withdrawals usually take?
Pending periods vary from no hold to 24-48 hours for reviews; once approved, transfers often arrive within 24 hours, though the total process can take 2-4 days.
What are common bonus wagering requirements?
Specialist reviews report wagering requirements commonly set at 30x–45x the bonus amount.
Real-Money PayID Payments: Minimums, Payout Timing and Bonus Conditions
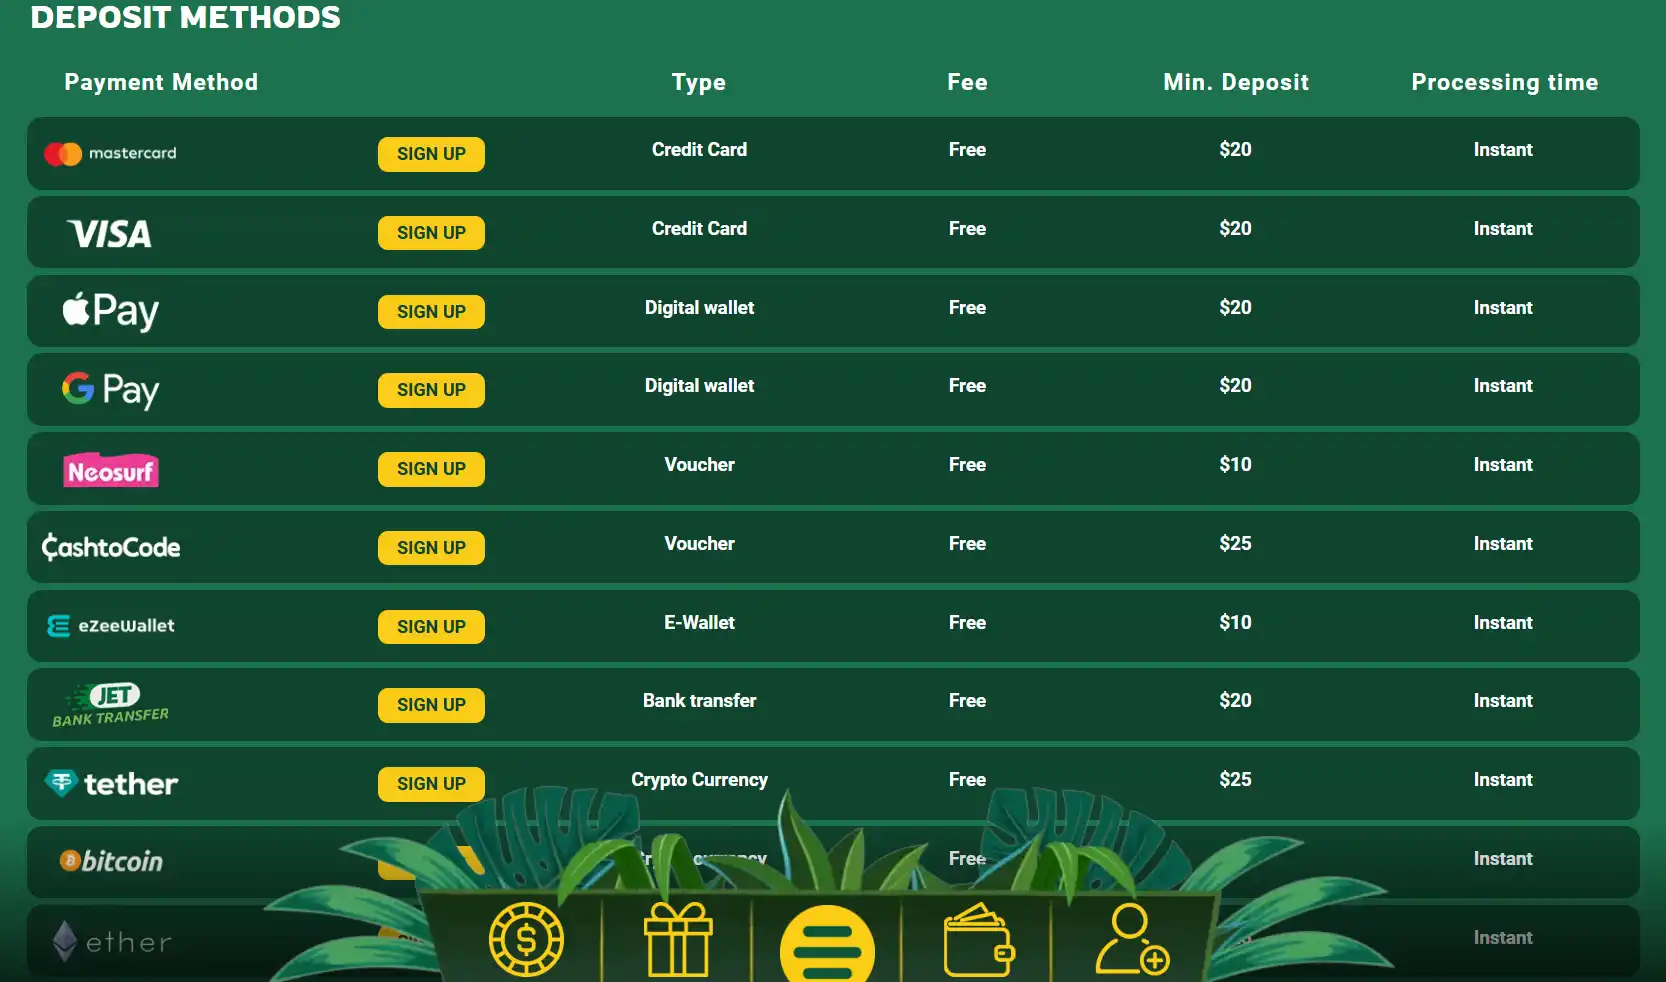
A minimum deposit is the smallest amount an operator will accept in one transaction; it is not a measure of what you should spend. Specialist reviews report PayID deposit minimums commonly falling between AU$10 and AU$20. The exact threshold is set by the operator and can differ from its withdrawal rules, so a low deposit minimum does not tell you how much you could later withdraw or whether a payment would be approved.
Withdrawal minimums are often higher. Specialist reviews place typical PayID minimum withdrawals in the AU$20–AU$50 range, but each operator sets its own terms. A balance below the stated threshold may not be eligible for a withdrawal request. Read the payment conditions together with the account rules, rather than assuming a deposit can be withdrawn in the same amount or under the same conditions.
Charges and net payout
PayID itself does not charge a transfer fee, but that does not rule out charges imposed by an operator. Specialist reviews report that some casinos charge AU$2–AU$5 for a withdrawal. Other specialist reviews describe deductions of AU$5–AU$10 when a withdrawal is below an operator’s internal threshold, with thresholds commonly stated as AU$100 or AU$200. These are reported practices, not a standard charge that applies everywhere. The written cashier terms matter: check whether a fee is fixed, whether a threshold triggers a deduction, and whether the amount shown is the gross request or the amount expected to reach the account.
A small fee can make a meaningful difference to a modest withdrawal. Before submitting a request, compare the amount you intend to withdraw with the stated minimum and any fee or threshold conditions. Do not assume that combining requests or making a larger request will improve the outcome; the operator’s rules determine how requests are handled.
Best New Australian Online Pokies: What to Know
It distinguishes Australian legal restrictions from offshore marketing claims and examines payment, bonus and game-credit…
Why a withdrawal can take longer
The time shown for a payment method is only one part of the process. An operator may first hold a withdrawal while it reviews the request, and a manual review can take longer than an automated one. Specialist reviews report operator pending periods ranging from no hold to 12 hours, while manual checks may take 12–24 hours or longer over weekends. First withdrawals and accounts selected for extra review have also been reported to take 24–48 hours at the slower end.
Those timings describe reported experiences, not a promise for an individual request. A payment can remain pending because the operator has not completed its review; only after it releases the funds does the transfer stage begin. The request time, review time, and transfer time should therefore not be treated as one guaranteed window. If a request remains pending, check its status and the operator’s stated process rather than assuming that PayID itself has failed.
Specialist reviews have also reported payout times ranging from around five minutes to 24 hours, depending on the operator and when the request was made. That range is not a dependable forecast: a fast payment in one case does not establish how another request will be handled. Review queues, verification checks and weekend processing can all affect the time before funds are released. Keep the request confirmation and any status updates so you can describe the issue clearly if you contact the operator.
Bonus conditions and real-money risk
A bonus may come with wagering conditions that limit when bonus funds or related winnings can be withdrawn. Specialist reviews report wagering requirements commonly set at 30x–45x the bonus amount. The exact calculation and eligible activity depend on the written terms, so a bonus figure alone does not show how much wagering is required. Also check the maximum bet permitted while wagering: exceeding that limit can void the bonus and associated winnings.
These payment details should not be read as an invitation to use real-money casino services from Australia. Under the Interactive Gambling Act 2001, providing online casino games, including pokies, to people physically located in Australia is illegal. PayID availability, published minimums or a bonus offer do not change that legal position, and they do not guarantee that an operator will approve or pay a withdrawal.
Does PayID charge fees for casino deposits or withdrawals?
PayID itself does not charge transfer fees, and reputable venues do not add fees for PayID transactions. Some casinos may charge a withdrawal fee of A$2–A$5, so check the casino’s terms.
How do I deposit money into online casino sites using PayID?
Use the PayID identifier shown for the payment in your bank’s payment process, and make sure it matches the PayID registered with your bank. Check the recipient details carefully before confirming, because a confirmed PayID transfer is irreversible.
What security measures are in place at casino sites that use PayID?
PayID is designed to support secure transfers through the NPP, but that does not certify a casino’s website, games, or handling of personal information. Check the recipient details before confirming a payment.
What does it cost to start?
PayID deposits commonly start at A$10–A$20, although some operators accept deposits from A$5. The casino’s stated minimum determines how much you need to deposit.
What is the minimum PayID deposit?
Typical PayID minimum deposits are A$10–A$20, while some operators accept as little as A$5.
Are online pokies legal in Australia?
No. Under the Interactive Gambling Act 2001, operators cannot legally provide real-money online casino games, including pokies, to people physically located in Australia.
 Fair Go Casino Bonus Australia: Welcome Offer and Terms GuideFair Go Casino Bonuses and Welcome Offer for Australia The headline value is ...
 Is Fair Go Casino Legit? Trust, Reputation and Licence ChecksIs Fair Go Casino Legit? Trust, Reputation and Licence Checks A trust assessm...