What “Fast Withdrawal” Means After a Casino Approves Your Request
A cashout has two separate stages: the operator’s review and the payment transfer. “Instant” can describe the second stage without saying anything reliable about how long the full process will take. If a request is waiting for approval, the payment has not yet been released, even when the chosen method can move funds quickly.
That distinction matters when you assess a claim about an easy or fast withdrawal. The clock does not necessarily start and stop at the same points across different services. An operator may first need to review the request; only after approval can the payment provider or bank handle the transfer. So a quick transfer after release is not the same as money arriving instantly from the moment you submit a request.
A specialist review of payment services described overall payout speed as depending on several factors. The practical point is that no single label captures the whole process. The operator’s handling and the payment route each have a part to play, and the slower stage determines when funds reach you. A fast payment rail cannot remove a delay that occurs before a request is approved.
Список казино
When choosing a casino for easy withdrawals, check what is actually known about payout times and payment requirements. Use this list to assess the available details before deciding what suits you.
1
JeetCity Casino
License
Curacao eGaming (Dama N.V.)
JeetCity is listed with a Curacao eGaming licence held by Dama N.V. The available information does not specify withdrawal methods or payout times.
2
LuckyVibe
License
Curacao Gaming Control Board OGL/2023/176/0095 (Hollycorn N.V.)
LuckyVibe is listed with a Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V. No payout speed or withdrawal method is specified in the available information.
3
Kingmaker
Payout speed
crypto ~90 minutes, fiat 1-5 days
Min. deposit
A$30
Kingmaker lists crypto payouts at around 90 minutes and fiat payouts at 1–5 days. Its minimum deposit is A$30.
4
Roby Casino
License
Curacao eGaming (Roby Games Ltd)
Roby Casino is listed with a Curacao eGaming licence held by Roby Games Ltd. The available details do not give withdrawal speeds or payment methods.
5
Playfina Casino
License
Curacao eGaming (Hollycorn N.V., since 2017)
Min. deposit
A$20-30 (depends on the offer)
Playfina Casino is listed with a Curacao eGaming licence held by Hollycorn N.V. since 2017. Its minimum deposit is A$20–30, depending on the offer.
6
Vegaz Casino
License
Curacao OGL/2024/1335/0780
Min. deposit
EUR 20
Vegaz Casino is listed with Curacao licence OGL/2024/1335/0780, and its minimum deposit is EUR 20. The available information does not specify payout times or withdrawal methods.
7
JustCasino
License
Curacao Gaming Control Board
JustCasino is listed with a Curacao Gaming Control Board licence. The available information does not specify withdrawal methods or payout times.
8
House of Pokies
License
international iGaming licence – jurisdiction not named in the source
Payout speed
PayID 1-24 hours
Min. deposit
A$30 (PayID from A$10)
House of Pokies lists PayID payouts at 1–24 hours and a minimum deposit of A$30, or A$10 when using PayID. Its licence is described as an international iGaming licence, but the jurisdiction is not named.
9
Ricky Casino
Payout speed
crypto under 1 hour, PayID 1-3 business days
Min. deposit
A$20 (A$30 to qualify for the bonus)
Ricky Casino lists crypto payouts in under an hour and PayID payouts in 1–3 business days. The minimum deposit is A$20, or A$30 to qualify for the bonus.
10
Lucky Dreams
License
Curacao
Min. deposit
A$20 (POLi)
Lucky Dreams is listed with a Curacao licence and a minimum deposit of A$20 when using POLi. No withdrawal speed or method is specified in the available information.
Approval comes before transfer
When you submit a withdrawal request, the operator may need to decide whether it can release the funds. Until that step is complete, a status such as “pending” does not mean that a bank transfer is already underway. It means the request has not yet reached the payment phase.
This is why it helps to read speed claims carefully. If a service advertises an instant payment, check what event the claim refers to: submission, approval, release, or receipt. Those are not interchangeable. A statement about transfer speed after release cannot promise that review will be immediate, and it cannot guarantee the time at which the funds will appear in your account.
The distinction is especially important for an initial cashout or a request that receives additional scrutiny. The details of those checks belong to the operator’s process, not to the speed of the payment network. Until approval is complete, comparing transfer methods alone gives you only part of the picture.
What “instant” can mean
PayID illustrates the difference between the two stages. It operates through Australia’s New Payments Platform, which supports real-time transfers between bank accounts. A specialist review has reported that, for a PayID cashout, funds can move instantly once the casino releases them. That description is about the movement of funds after release; it does not establish how quickly an operator will review every request.
Under-1-Hour Casino Withdrawals in Australia: What Counts
A withdrawal involves operator approval, eligibility checks and payment delivery, so a quick transfer alone…
Keep the wording precise when you compare claims. “Instant after approval” leaves room for a review period beforehand. “Instant withdrawal,” without that qualification, can sound as if the whole journey—from clicking the request button to seeing money in an account—takes no time. It does not necessarily mean that.
Even when the payment phase is quick, a receiving account may not display a transfer at the exact moment you expect. The operator’s release and the arrival you can see are different points in the process. If a status has not changed, first establish whether the request is still under review or has been sent for payment. That helps you avoid treating a pending request as a failed transfer—or assuming that a payment has been initiated when it has not.
Read the claim as a sequence
A useful way to assess any payout statement is to separate it into questions:
Has the request been submitted?
Has the operator approved and released it?
Is the payment provider processing it?
Has the receiving account shown the funds?
These are stages, not synonyms. A time claim may refer to only one of them. If the wording does not say where the timing begins, do not assume it covers the complete process. Look for the operator’s explanation of review and release, as well as the information for the payment method.
In Australia, the Interactive Gambling Act 2001 prohibits operators from providing online casino-style services—including slots, poker, blackjack and roulette—to people located in the country. Be cautious about treating offshore services or their payout claims as ordinary local consumer offerings.
The central distinction remains simple: approval is an operator decision; transfer is the movement of funds after release. A payment method may be capable of fast transfers, but that capability alone cannot tell you when a request will be approved or when you will see the money. When comparing claims, check which phase the stated speed actually covers.
PayID Payouts: Fast Transfers, With Limits to Check
PayID is part of Australia’s bank-to-bank payment infrastructure, not a casino payment service in its own right. It operates through the New Payments Platform (NPP), with transfers processed in real time through the Osko network. That infrastructure can move money quickly once a payment has been released, but it does not determine when an operator approves or sends a withdrawal.
There is an important legal distinction for Australians. Under the Interactive Gambling Act 2001, it is illegal for operators to provide real-money online casino games, including slots and table games, to people physically located in Australia. A payment method’s availability or speed does not make an online casino service lawful. The information here explains how PayID transfers work; it is not a recommendation to use a real-money casino service.
When a PayID payment is described as instant, the claim relates to the transfer stage, not necessarily the whole cashout. A request can still be waiting for the operator to release it before the bank-to-bank movement begins. Once released, PayID’s real-time design may allow the funds to move promptly, but the system cannot bypass an operator’s own handling or make a pending request complete.
That difference matters when you see claims about an easy withdrawal or a fast payout. The relevant question is not simply whether PayID supports real-time transfers. You would also need to know what the stated processing time covers: the operator’s review, the time until release, or only the transfer after release. A speed claim that leaves this unclear can give an incomplete picture of when money might arrive.
Best New Australian Online Pokies: What to Know
It distinguishes Australian legal restrictions from offshore marketing claims and examines payment, bonus and game-credit…
Limits are another point to check in any payment terms. A specialist review reports that reputable services offering PayID publish minimum and maximum withdrawal limits clearly. Treat that as a reason to look for the written terms, not as a guarantee that every service displays the same limits or applies them in the same way. Check whether the stated figures apply to each transaction, and whether separate conditions affect the amount that can be withdrawn.
A limit can make a fast transfer less useful if the amount you intend to receive cannot be sent as one payment. Operator policy may also affect how a larger withdrawal is released. Read the relevant conditions before relying on a headline about speed, and make sure the limit is specifically for withdrawals rather than deposits. Those are different transaction types and may have different rules.
PayID also depends on correct payment details. The identifier used for a transfer must correspond to the intended recipient, so an error can prevent a smooth payment. Do not assume that a familiar payment label means a transfer will be reversible or that support can resolve a mistake immediately. Confirm what the written instructions say before acting, and do not send money to an account or identifier you cannot verify.
Do
Verify the intended recipient's identifier
Confirm written instructions before acting
Use accounts linked to your profile
Don't
Assume a transfer is reversible
Use unfamiliar payment identifiers
Send money to unverified accounts
For a careful comparison, separate three things: the payment network, the operator’s release of funds, and the applicable withdrawal conditions. PayID and Osko describe the transfer infrastructure; they do not set an operator’s withdrawal limits or guarantee that a request will be approved. A responsible description of speed should make clear that real-time transfer capability begins only after release, while clear terms should identify the relevant limits.
If the terms do not explain the withdrawal minimum, maximum, or how a payment is handled, do not fill in the gaps from an “instant” label. Ask for clarification before relying on the claim. A fast payment rail can shorten the final movement of funds, but it cannot make unclear conditions clearer or change the legal status of a service.
Real-Money Withdrawals Start With Verification
A withdrawal can be held while an operator checks who is requesting it. That makes identity verification part of the cashout process, not a detail to leave until money is waiting to be released. Completing the check in advance can significantly speed up later withdrawals, although it does not guarantee that every request will be approved without further review.
A specialist review describes first withdrawals as a point when identity documents may be requested. Treat that as a possibility rather than a fixed rule: the timing and scope of checks can vary. If a verification request arrives, read it carefully and respond through the account’s official process. If the instructions are unclear, ask the operator what it needs before sending information. Do not assume that a submitted document has been accepted until the account reflects that the check is complete.
Same-Day Payout Casinos in Australia: Cash-Outs Explained
Withdrawals can involve account checks, operator approval and payment processing; Australian law prohibits online casino-style…
Pay attention to whether the details on your account match the information you provide for verification. An inconsistency can leave the operator unable to confirm that the account belongs to you, delaying the review. Use only accounts linked to your profile when requesting a withdrawal; details that do not match may prompt additional scrutiny. Keep your profile information accurate and resolve errors through the operator’s stated support channel rather than trying different details at cashout.
It is also sensible to check the account’s verification status before relying on a balance being available promptly. A pending identity check can hold up processing even when the withdrawal form accepts your request. Submitting a request is not the same as completing the checks required before funds can be released.
There is an important legal context for Australian readers. Under the Interactive Gambling Act 2001, it is illegal for operators to provide real-money online casino games to people physically located in Australia. A verification process on an offshore platform does not change that legal position, nor should it be treated as proof that the service is authorised to offer casino games in Australia. This information is not an invitation to use such a service.
If you already have an account with a platform, avoid sending identity documents through links in unsolicited messages. Sign in through the platform’s own known access route and check that a request appears within the account, or contact support using details shown there. Share only what the verification process requests, and be cautious if the instructions ask you to send sensitive information through an unrelated channel.
Getting verification completed early can remove one potential obstacle from a later cashout, but it cannot make the entire process immediate. The operator may still need to review a request, and the payment stage follows only after approval. For any service you encounter, read its terms and privacy information before sharing personal details, and do not treat a fast-withdrawal claim as a substitute for checking how identity reviews work.
Why Your Withdrawal May Go Back to Your Deposit Method
A withdrawal is not always sent wherever you choose. Operators generally require funds to be returned through the same method used to deposit, where that is possible. So if you funded an account through one payment route, the withdrawal may be directed back through it rather than to a different card, bank account or digital wallet.
This is a payment-matching condition, not a statement about how quickly the transfer will arrive. The destination can affect the route a payment takes, but matching your deposit method does not by itself guarantee that a request will be approved or paid immediately. The operator still has to handle the request under its own procedures.
Changing details can make the request less straightforward. If the withdrawal information does not match the method or account associated with the deposit, the operator may pause to examine the difference. That is a reason to use the same PayID details for withdrawals as for deposits, and to request payment only to accounts linked to your profile. A mismatch may prompt additional scrutiny rather than a direct transfer.
Before submitting a request, check which method the operator expects to use for the return payment. Confirm that the relevant account or payment identifier is still available to you and that its details match those associated with your profile. If you have changed accounts or can no longer access the original method, contact the operator through its stated support channel before making a request. Do not assume you can substitute another destination without affecting how the request is handled.
The phrase “where possible” matters. It leaves room for cases in which the original route cannot be used, but it does not mean a different method will automatically be accepted. The operator may need to explain what alternatives it permits and what information it requires. Follow the instructions provided for your account, and keep a record of the method and details you submitted so you can describe any discrepancy clearly if asked.
When comparing an online casino with easy withdrawal claims, treat the payment route and the withdrawal conditions as separate things to check. Clear terms should explain whether funds must go back to the deposit method and what happens if that route is unavailable. A claim about a simple cashout does not remove the matching requirement, and a different destination should not be treated as a shortcut around it.
There is also an important legal context for readers in Australia: operators are prohibited from providing real-money online casino games to people physically located in the country. This explanation is not an endorsement of using such services. If you come across withdrawal terms, understanding the method-matching rule can help you recognise why a payment may not go to the destination you first expected.
Keep the distinction in mind: the original method may determine where a payment is sent, while separate operator procedures determine whether the request can proceed. Checking those conditions before depositing is more useful than assuming that any later change of destination will be accepted.
How the Payment Method Can Change the Wait
A payment route can affect how long an approved withdrawal takes to reach you, but it does not determine when the operator approves the request. E-wallets and bank transfers can have different transfer times after release; the time shown for the payment phase should not be read as a promise that the full wait begins and ends with your request.
A general timing comparison in casino payment information places e-wallet withdrawals at within 24 hours in typical cases, while bank transfers and card payments may take several days. A specialist review also described e-wallet transactions as completing within hours rather than days. Treat those as reported estimates, not guarantees: the payment provider, the operator’s handling, and the timing of the transfer can all affect what you experience.
Traditional bank transfers can take longer. One specialist review reported that completion could take as many as five business days. That figure is a reported upper timeframe, not a prediction for every transfer. A bank may also take time to display a payment after it has been sent, so the operator’s release time and the point at which the funds appear in your account are not necessarily the same.
With an e-wallet, the transfer may be quicker once released, but that does not remove the operator’s approval step. Nor does choosing a faster route ensure the same result at every operator. Available methods and their stated processing times vary, so the terms for the specific service matter more than a broad claim about e-wallets or banks.
Before relying on a payment estimate, check which phase it describes. A stated processing window might cover the operator’s handling, the provider’s transfer, or both. If the wording is unclear, ask the service to clarify when its clock starts and whether the estimate is for approval or receipt. Keep a record of the stated timing and any status update, especially if the transfer appears to have been released but has not reached your account.
Payment choice can also be limited by the service’s available options. A review of Australian-facing payment methods lists PayPal and Skrill among e-wallets, alongside bank transfers and card payments; it also notes that some services offer cryptocurrency. This does not mean every method is offered by every operator, or that every route supports withdrawals. Check the withdrawal options and timing shown for the particular account rather than assuming a deposit method can also be used to receive funds.
There is an important legal context for anyone in Australia: the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games, including slots and table games, to people physically in the country. Payment comparisons should not be taken as an endorsement or an invitation to use such a service. If you are reviewing payment information, distinguish general timing descriptions from any claim that a withdrawal will be immediate from request to receipt.
E-wallets
Typically processed within 24 hours, often completing within hours.
Bank Transfers
Can take several days, with some reports indicating up to five business days.
Card Payments
Generally take several days to reach the account after the operator's release.
Australian Payment Options and Their Trade-Offs
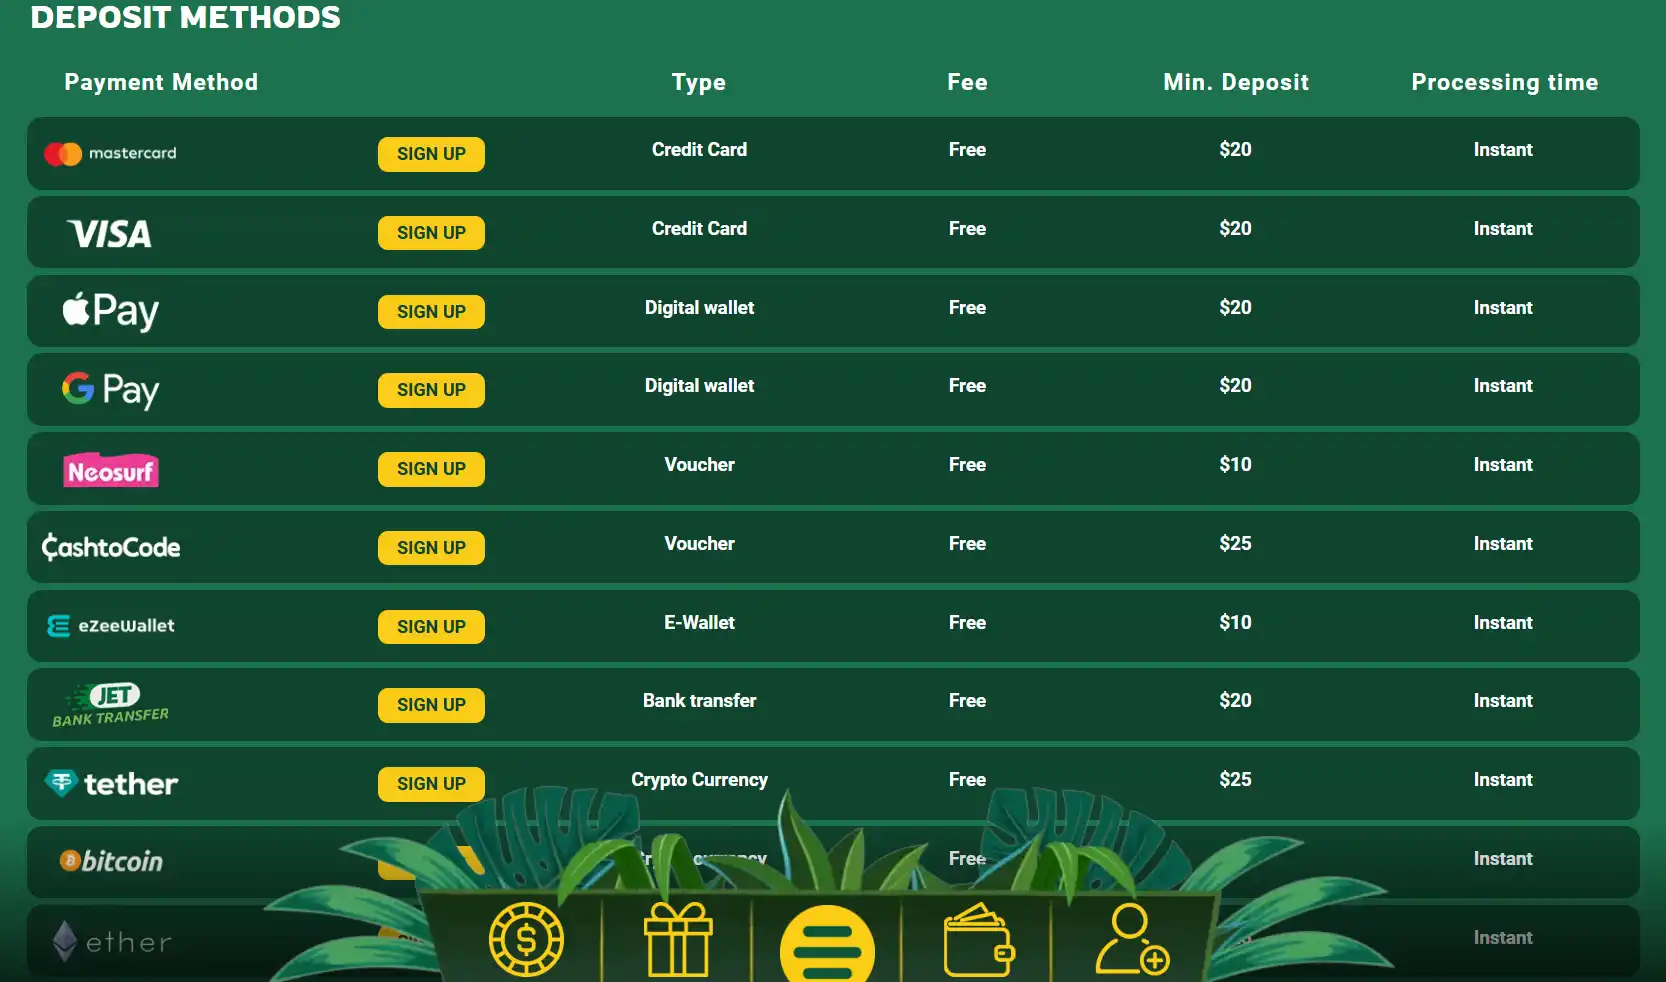
Payment options can look similar on a cashier page while serving different purposes. A specialist review of real-money platforms accessible to Australian players describes a range that includes debit cards, PayPal and Skrill e-wallets, bank transfers and, at some platforms, cryptocurrency. Availability is not uniform, and a listed deposit method does not necessarily provide a route for cashing out.
That distinction is particularly important with prepaid products. A specialist review reports that vouchers such as Neosurf are generally presented for deposits rather than withdrawals. They can therefore leave a player needing another payment route to receive funds. Before entering payment details, check what the terms say about both directions of a transaction; the names shown on a deposit screen alone do not establish that a method can be used for withdrawals.
E-wallets and bank transfers may be listed for both deposits and withdrawals, but each operator sets its own available options. A payment provider appearing in a cashier menu is not proof that every account can use it, or that it is available for every transaction. Cryptocurrency is also reported as an option at some platforms, not as a universal feature. Its presence does not remove the need to check whether the platform allows withdrawals through that route and what conditions apply.
There is an important legal context for Australian readers: the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in Australia. The payment methods described in reviews of offshore platforms are not an endorsement or a recommendation to use them. A page listing an option does not make the underlying service lawful or mean the option is accessible to you.
If you encounter payment details on a platform, avoid treating a familiar brand or a short menu as a guarantee of protection or a workable cashout. In particular, do not assume that a deposit method can receive money back. The practical distinction is between methods that may be used to fund an account and those an operator says it can use for withdrawals; the latter needs to be stated clearly in the platform’s terms. That is a basic limitation to understand, not a promise that funds can be recovered.
Slot Withdrawals Still Depend on the Cashout Process
A win on a slot does not make the withdrawal automatic. The balance may be ready to request, but the operator still has to approve the cashout before the chosen payment route can deliver the funds. The game itself does not determine how quickly that process moves.
A specialist review notes that payment speed can depend on several factors. For a slot withdrawal, the practical distinction is between the casino’s handling of your request and the transfer after release. The operator may need to review the request; only once it is approved does the payment method’s own timing become relevant. An advertised instant withdrawal should therefore be understood as a claim about the payment stage, not a promise that money will arrive as soon as you press the button.
Slot Cashout Process
1
Submit Request
Check the available balance and follow the operator's stated request process.
2
Await Approval
Wait for the operator to review the request and change the status from pending.
3
Payment Transfer
Once released, the funds move via the chosen payment route based on its specific timing.
The payment route can make a noticeable difference after approval. E-wallet cashouts are described as taking up to a day to process, whereas card payments and bank transfers can stretch across several days. These are reported timeframes, not a guarantee for a particular request: the casino’s own handling and the payment provider’s processing both matter. Check the terms for the selected route before relying on a particular arrival time.
When you request a slot cashout, check that the amount shown as available is the amount you intend to withdraw, then follow the operator’s stated request process. Keep the confirmation and any status update so you can tell whether the request is awaiting approval or has been released for payment. If the status is unclear, ask support which stage it has reached rather than assuming a delay means the transfer has failed.
Treat “easy” as a description of a clear process, not a shortcut around approval. A straightforward request can still take time to clear the operator’s review and then travel through the payment route. Knowing which stage is pending gives you a more useful expectation than the slot’s result or a broad speed claim.
Live Casino Cashouts: Allow for Review Before Payment
A live table may make play feel immediate, but that does not make a cashout immediate. A withdrawal still has to pass through the operator’s approval process before the payment provider can send it. The word “instant” may describe only the transfer after release, not the time from submitting a request to receiving funds.
Online Casino Payment Methods for Australian Players
A practical guide to how bank links, wallets and other payment routes work, and what…
That distinction matters when assessing claims about easy withdrawals from live casino services. A specialist review reported cases where a site advertised instant withdrawals but internal checks delayed release for as long as 24 hours. That is a report about particular cases, not a dependable timetable for every operator. It does show why an advertised payment speed should not be treated as a promise about the whole cashout process.
A live-casino session does not bypass those checks. The operator may still need to review the account or request identity documents, especially if it is a first withdrawal. A specialist review also identified first-time verification, requests above $2,000 and bank processing windows as possible sources of delay. Where a withdrawal exceeds $2,000, the operator’s manual-review process should be made clear in its terms. Even when approval is complete, the receiving bank’s processing can affect when the funds appear.
Before relying on a speed claim, look for separate information about approval and payment. Check whether the stated time begins when you submit the request or only after the operator releases it, and whether the terms explain any review that can delay release. If the wording does not make that distinction, do not assume that “instant” means money will arrive straight away.
There is also an important Australian context: under the Interactive Gambling Act 2001, operators may not provide real-money online casino games, including live table games, to people physically in Australia. This includes services offering live blackjack or roulette. The cashout language used by an offshore service does not change that legal position.
Treat a fast-payment claim as a description of one stage, not a guarantee of the full process. An operator review can come first, and payment processing can follow only after approval.
Check Bonus Wagering Before Requesting a Withdrawal
A bonus can change whether a balance is available to withdraw. Before accepting a deposit bonus or submitting a cashout request, read the terms to see whether wagering conditions apply and what funds count towards them. A balance shown in an account is not necessarily a withdrawable balance while applicable conditions remain unmet.
The basis matters. A specialist review notes that wagering may be calculated on the bonus alone or on the combined deposit and bonus; the bonus-only basis is preferable because it does not include your deposit in the amount subject to wagering. Check the wording rather than relying on a headline offer or a short summary. If the terms are unclear about which balance is covered, ask the operator to explain before you accept the bonus.
Also check what the terms say about completing the requirement and requesting a withdrawal. If you request a cashout before meeting applicable conditions, the request may not proceed as expected. Do not assume that depositing your own money makes the full account balance immediately withdrawable when a bonus is active. The terms determine how the offer affects the funds.
If you decide the conditions are not suitable, declining the bonus can avoid taking on its wagering rules. If you have already accepted it, look for the account’s bonus status and the precise conditions attached to that offer before acting. Keep a record of the terms you accepted, especially if the offer wording and the account display do not appear to match.
This is a practical check, not a recommendation to use a real-money casino. Australian law prohibits operators from providing online casino games for real money to people in Australia. If you encounter bonus terms, understanding their effect can help you avoid treating restricted funds as ready to withdraw.
Online Pokies Instant Withdrawals in Australia
A payout can move quickly only after the casino reviews and releases the request; the…
Cashout Limits, Fees and Timing to Confirm in Advance
A withdrawal can be affected by more than the balance shown in your account. Before submitting a request, read the cashout terms for the specific service and payment route. The amount available to withdraw may be restricted by operator policy, and the stated maximum for one transaction may not tell you how much you can receive across a longer period.
A specialist review reports that some services set separate weekly or monthly cashout caps in addition to per-transaction maximums. Check each limit: a request could fit within the single-payment cap but still exceed the remaining allowance for the relevant period. Also look for instructions on how the service handles a balance above a limit, including whether it may be paid in instalments under the operator’s policy.
Fees need their own check. A report by filmink.com.au notes that a fee may apply to a PayID withdrawal; that is not a guarantee that every service charges one, or that the charge is the same everywhere. Review the terms and any confirmation screen for a fee imposed by the service, and check whether a payment provider or bank may charge separately. If the amount shown is unclear, ask the service to confirm the deduction before proceeding.
Timing information should be read alongside the limits and fees, not as a promise that the whole request will be completed within a stated period. Terms may distinguish the time taken to review and approve a withdrawal from the time taken to send the payment. A request may also be handled differently if it exceeds a stated cap or is split into instalments. Compare the service’s published processing description with the payment method shown for your account.
Keep a record of the applicable terms and the amount requested. If a displayed limit, fee or timing estimate conflicts with the written conditions, pause and seek clarification rather than assuming the more favourable figure applies. The useful comparison is the net amount you can request, any charges deducted, and the conditions attached to receiving it—not simply a headline claim about easy cashouts.
What are easy withdrawal casinos?
They are sites that claim to make cashouts straightforward or quick. A fast payment method only speeds up the transfer after the operator approves and releases your request.
How do you choose the best easy withdrawal casino site?
Check how the site handles approval and release, whether it clearly publishes withdrawal limits, and what verification it requires. Also check that the service is lawful where you are: Australian law prohibits operators from providing online casino-style games to people located in Australia.
How fast are withdrawals?
It depends on both the operator’s approval process and the payment method. E-wallet withdrawals are often completed within hours and typically processed within 24 hours; bank transfers can take up to five business days. PayID can transfer funds in real time once the operator releases them.
What payment methods are available?
Options used by Australian players include credit and debit cards, PayPal and Skrill e-wallets, and bank transfers; some sites also offer cryptocurrency. PayID can support real-time bank-to-bank transfers, while prepaid vouchers such as Neosurf are generally for deposits rather than withdrawals.
 Fair Go Casino Bonus Australia: Welcome Offer and Terms GuideFair Go Casino Bonuses and Welcome Offer for Australia The headline value is ...
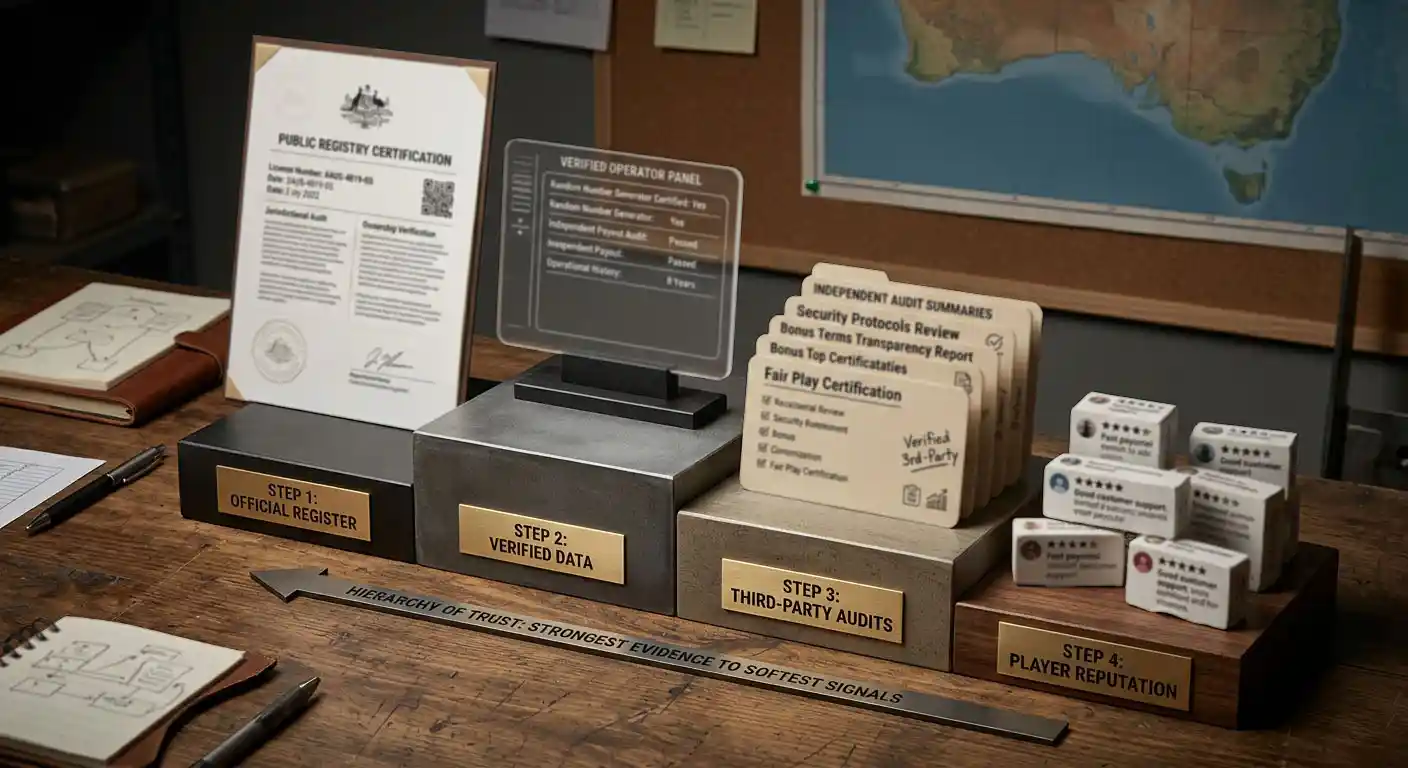 Is Fair Go Casino Legit? Trust, Reputation and Licence ChecksIs Fair Go Casino Legit? Trust, Reputation and Licence Checks A trust assessm...